Data as of 7 October 2026.
Steel Sector State Aid Support
EU state aid rules allow competitiveness enhancing support to viable steel companies but do not allow public aid to steel manufacturers in financial difficulties. Nor do they allow government support that gives a steelmaker an advantage over its competitors (although aid for environmental protection or research and development is normally allowed). Regional aid and support for plant closure are also prohibited in the steel sector. The table below lists 55 examples where government support was considered and / or approved by the European Commission or national governments.
| Year | Country | Company | Facility | Project Type | Aid €m |
| 1994 | Portugal | Siderurgia Nacional | Seixal | BF closure, new EAF | 306 |
| 1995 | Austria | Voest Alpine Erzberg GmbH | Erzberg | Op losses & mine closure | 29.7 |
| 1996 | Ireland | Irish Steel | Haulbowline | Restructuring aid | 50 |
| 1998 | Bulgaria | Kremikovtsi Steel | Kremikovtsi Steel | Capex support | 222 |
| 2002 | Finland | Imatra | Imatra Steel Oy Ab | Environmental upgrade | 1 |
| 2003 | Romania | Mittal Steel | Petrotub | Debt forgiveness | 26 |
| 2006 | Belgium | Duferco | Wallonia-based firms | Share purchases | 211 |
| 2009 | Latvia | Liepājas Metalurgs | Liepāja | Loan guarantee | 89 |
| 2010 | Austria | Voestalpine Stahl | Linz | Clean up support | 146 |
| 2010 | Germany | Salzgitter | Flachstahl | Environmental protection | 19 |
| 2011 | Norway | Finnfjord AS | Finnfjord | Environmental protection | 21 |
| 2013 | Czech Republic | ArcelorMittal | Nová Huť | Environmental protection | 15 |
| 2013 | Turkey | Erdemir | Madencilik Sanayi ve Ticaret | Pellet plant | 828 |
| 2015 | Italy | Ilva | Taranto | Loan subsidy plus capex | 2000 |
| 2015 | Norway | Tisir Titanium & Iron | Tyssedal | Demonstration plant | 13 |
| 2016 | United Kingdom | Tata Steel | Dalzell | Government guarantee | See note |
| 2021 | Poland | Jastrzębska Spółka Węglowa | JSK Koks | Capex support | 14 |
| 2021 | United Kingdom | Celsa | Cardiff | Energy efficiency | 3 |
| 2022 | Spain | Celsa | Celsa Spain | Business rescue | 550 |
| 2022 | Sweden | H2GS | Boden plant | Green steel | ECA g'tees |
| 2022 | Sweden | HYBRIT | Pilot plants | Green steel | 143 |
| 2023 | Belgium | ArcelorMittal | Ghent | Decarbonisation | 280 |
| 2023 | France | ArcelorMittal | Dunkirk | Decarbonisation | 850 |
| 2023 | Germany | ArcelorMittal | Duisburg | Decarbonisation | n/a |
| 2023 | Germany | ArcelorMittal | Hamburg | Demonstration plant | 55 |
| 2023 | Germany | Salzgitter | Salzgitter | Decarbonisation | 1000 |
| 2023 | Germany | thyssenkrupp | Project tkH2Steel | Decarbonisation | 2000 |
| 2023 | Hungary | Dunaferr | Dunaferr | Employment costs | 42 |
| 2023 | Italy | Acciaierie d’Italia | DRI d'Italia | Pilot plant | 35 |
| 2023 | Poland | Jastrzębska Spółka Węglowa | JSW Plant | Energy cost support | 4 |
| 2023 | Slovakia | USSK | Košice | Decarbonisation | 300 |
| 2023 | Slovenia | Slovenian Steel Group | SIJ Acroni | Energy costs | 1 |
| 2023 | Slovenia | Slovenian Steel Group | SIJ Metal Ravne | Energy costs | 1 |
| 2023 | Spain | ArcelorMittal | Gijón | Decarbonisation | 450 |
| 2023 | UK | Tata Steel | Port Talbot | Decarbonisation | 580 |
| 2024 | Czech Republic | Třinecké železárny | Třinec | Capex support | 20 |
| 2024 | France | ArcelorMittal | Fos-sur-Mer | Capex support | 15 |
| 2024 | Germany | Stahl Holding Saar | Saarstahl and Dillinger | Decarbonisation | 2600 |
| 2024 | Germany | Vallourec | Pipe at Düsseldorf / Mülheim | Restructuring aid | 3 |
| 2024 | Romania | Liberty Galați | Galați | Business rescue | 150 |
| 2024 | Sweden | H2GS | Boden plant | Green steel | 265 |
| 2024 | Sweden | SSAB | Luleå | Decarbonisation | 128 |
| 2024 | Switzerland | Swiss Steel / Beltrame | Gerlafingen / Steeltec | Energy cost support | 20 |
| 2024 | United Kingdom | British Steel | Scunthorpe & Teesside | Decarbonisation | 345 |
| 2025 | Germany | ArcelorMittal | Bremen & Eisenhüttenstadt | Decarbonisation | 1300 |
| 2025 | Italy | Acciaierie d’Italia | Taranto | Rescue aid | 200 |
| 2025 | Italy | Arvedi AST | Terni | Environmental protection | 97 |
| 2025 | Italy | JSW Steel Italy | Piombino | Rail mill development | 33 |
| 2025 | Netherlands | Tata Steel Netherlands | IJmuiden | Decarbonisation | 2000 |
| 2025 | Poland | ArcelorMittal Poland | Dąbrowa Górnicza | Capex support | 234 |
| 2025 | Spain | ArcelorMittal | Avilés | Energy efficiency | 4 |
| 2025 | Sweden | Stegra (formerly H2GS) | Boden plant | Green steel | 35 |
| 2025 | UK | British Steel | Scunthorpe | Business rescue | 434 |
| 2026 | Italy | Acciaierie d’Italia | Taranto | Rescue aid | 390 |
| 2026 | Spain | Hydnum Steel | Puertollano | Green steel | 60 |
Analysis of Steel State Aid by Country
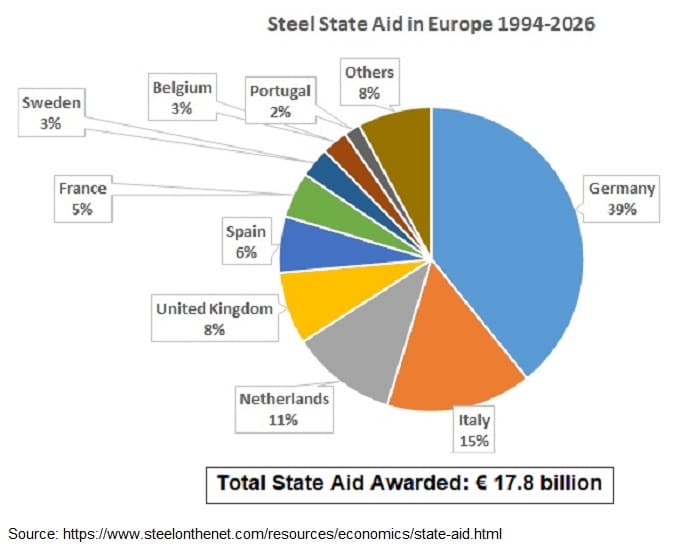
For analysis of European steel state aid by location of recipient plant [data as of 7 October 2026], see chart below. The chart covers the EU plus Norway, Switzerland and the United Kingdom; it excludes Turkey.
Notes
- 1994: EC approval of Portuguese Government support for Siderurgia Nacional's blast furnace closure / EAF investment at Seixal was conditional on the workforce being reduced by 1,798 employees by the end of 1996.
- 1995: Aid to Voest Alpine Erzberg comprised ATS 272m (€19.8m) to cover operating losses [operating aid] plus ATS 136m (€9.9m) for closure of iron ore mines in a safe and environmentally-friendly manner [closure aid], thus ATS 408m (€29.7m) steel state aid in total.
- 1996: Aid to Irish Steel was equivalent to IR£29m. Calculation above assumes exchange rate of €1.27 per Irish punt.
- 1998: Kremikovtsi went bankrupt in August 2008. The Bulgarian government then initiated proceedings to recover the aid, as part of the liquidation proceedings.
- 2003: Legality of the debt relief given to the Mittal Steel Roman seamless tube plant (Petrotub) was subsequently questioned by the European Commission in 2007.
- 2006: Wallonia firms involved in the 2006–2011 government support included Duferco Clabecq, Duferco La Louvière and Carsid. This aid was subsequently declared to have been illegal.
- 2011: Support for Norway's Finnfjord was for investment in an energy recovery system for the production of ferrosilicon. The investment would allow the ferroalloy producer to generate 224 GWh of electricity and 125 GWh of steam per year.
- 2013: Environmental support for ArcelorMittal Nová Huť in Ostrava in 2013 was for an upgrade of the sinter plant dedusting equipment. Distortion of competition because of this aid was expected to be limited.
- 2013: Support for Erdemir's pellet plant was an investment incentive awarded by the Turkish Government. As Turkey is outside the EU and the European Economic Area, this support was not subject to EU state aid rules, and it is excluded from the analysis by country above.
- 2015: Government support to Ilva was subsequently challenged: the European Commission deemed that some of this aid had been illegal and in 2017 requested Ilva to repay €84m of interest subsidy.
- 2015: Norway's Tisir Titanium & Iron produces titanium dioxide (TiO2) slag and high purity pig iron. State Aid was for construction of a full-scale demonstration plant assessing a novel roof technology in the furnace that was expected to bring reduced energy consumption and reduced emissions of CO₂ to the smelting production process.
- 2016: Regarding the sale by Tata Steel of the Dalzell plant to Liberty House, an implied state aid issue was uncovered in 2021 (even though no cash changed hands). This is because the sale contract included a clause committing the Scottish government to protecting Tata from future liabilities in the event of a Liberty bankruptcy. This guarantee was deemed to be potential state aid in 2021 and the matter was to be referred to the European Commission for further investigation.
- 2022: Rescue of Celsa Spain was dependent on creditor approvals (Goldman Sachs and Deutsche Bank).
- 2023 Salzgitter support is for the firm's SALCOS project, involving investment in new electrolyser and DRI-based EAF.
- 2023: Dunaferr went into liquidation in December 2022. Some questions appear to hang over the legality of state support given by the Hungarian government, to cover wage costs in early 2023. Some press reports also question whether recent ETS-related fines of around €600m should have been waived by the Hungarian Government.
- 2023: Aid for USSK's decarbonisation project is to be provided under the European Union's Recovery and Resilience Plan.
- 2023: Condemnation arose of the aid for SIJ Group subsidiaries in Slovenia when it transpired that the parent company had approved a dividend of €5.8m.
- 2023: Undertaking from the United Kingdom Government to Tata Steel was to grant up to £500m for the transition of Port Talbot in South Wales to low carbon steelmaking. Total project cost was estimated at £1.25bn.
- 2023: Discussions between the UK Government and British Steel centre on closure of Scunthorpe blast furnaces and investment in new EAF facilities at Scunthorpe and at Teesside. Talks with China's Jingye Group were still ongoing in November 2023. Unions expressed concern about the potential for 2,000 job losses.
- 2021: Celsa UK support was a grant towards a static VAR compensator for the high voltage EAF in their Cardiff melt shop.
- 2024: Financial support for Vallourec related to relocation of pipe-making from Düsseldorf and Mülheim to Brazil; and was for training and redeployment of the German workforce.
- 2024: Czech government support for Třinecké železárny was for investment in a cold briquetting plant to assist with decarbonisation. The new iron ore briquetting facility will replace sintering, and is expected to be commissioned in mid-2027.
- 2024: ArcelorMittal capex support at Fos-sur-Mer was for installation of a new ladle furnace.
- 2024: Swedish support for SSAB is for installation of a new EAF melt shop at Luleå. Danieli will be supplying two new EAFs with a combined capacity of 2.5 Mt/yr plus secondary metallurgy (as well as continuous caster and a strip mill) for the Luleå mini-mill project.
- €20m subsidy figure for Switzerland in 2024 is only approximate. In fact, €39.8m of support to cover high energy costs is being given to Swiss Steel and to Beltrame, as well as to two aluminium producers (Constellium and Novelis).
- 2025 aid for JSW Steel Italy in Piombino was for rail mill modernisation, including an upgrade of the roughing mill, the tandem mill and rail-hardening equipment. The investment will double the current rail production capacity from 300,000 to 600,000 tonnes a year and will allow an increase in rail length from 108 to 120 metres.
- 2025: Aid for ArcelorMittal Spain in Avilés comprises two projects (i) €2.8m for renovation of a gasometer to reduce natural gas consumption (ii) €0.74m of aid for modernisation of the pickling line.
- 2024: Support for Liberty Galați in Romania was a state-backed credit of up to €150m from Exim Banca Românească, granted in December 2024 to restart production. This followed an earlier €142m Exim Bank loan in December 2023.
- 2025: €200m was allocated to Acciaierie d'Italia by Italian cabinet decree in June 2025, to guarantee production continuity at Taranto while the company was in extraordinary administration.
- 2025: Arvedi AST figure is the amount applied for under a Development Contract for Environmental Protection, as part of a programme agreement for the environmental modernisation of the Terni works (total programme value €1.13bn).
- 2025: Support for Tata Steel Netherlands is based on a non-binding Joint Letter of Intent signed in September 2025 with the Dutch Government and the Province of North Holland, covering the first phase of transition to low-CO₂ steelmaking at IJmuiden. The deadline for a final agreement was later extended to 1 March 2027.
- 2025: Support of up to PLN 1bn for ArcelorMittal Poland was under negotiation with the Polish Government in June 2025, for blast furnace modernisation at Dąbrowa Górnicza. Calculation above assumes an exchange rate of PLN 4.28 per euro.
- 2025: Stegra aid was an additional grant of SEK 390m from the Swedish Energy Agency under the Industrial Leap programme, conditional on the company securing sufficient capital to complete the Boden plant.
- 2025: Following the Steel Industry (Special Measures) Act 2025, the UK Government spent £377m between April 2025 and January 2026 to keep British Steel's Scunthorpe blast furnaces operating, according to the National Audit Office. The funding is classified as a loan.
- 2026: The 2026 rescue loan to Acciaierie d'Italia of up to €390m was approved by the European Commission in February 2026 and has since been drawn down in several tranches.
- 2026: Aid for Hydnum Steel was a €60m grant under the Spanish PERTE programme for industrial decarbonisation, for a new green steel plant at Puertollano with total capex of about €1.65bn.
Funding Agencies
Agencies involved in the above steel state aid included the following.
- ENOVA SF (owned by the Norwegian Ministry of Climate and Environment)
- EU Recovery & Resilience Plan
- European Globalisation Adjustment Fund
- European Investment Bank
- European Post-Covid Recovery Fund
- Ministry of Enterprises and Made in Italy (MIMIT)
- Norwegian Energy Fund
- Polish Government Environmental Fund
- Swedish Recovery and Resilience Facility (Industrial Leap programme)
- The Spanish PERTE programme
- The UK Industrial Energy Transformation Fund
For short overview of the rules concerning public aid for the steel sector, see presentation from DG Competition.
Back to Knowledge Base Index