Options in a New Policy Landscape
The UK Steel Strategy
The UK Steel Strategy, published by the Department for Business and Trade in March 2026, is the most comprehensive statement of industrial policy for the domestic steel sector in a generation. For most of the sector it provides meaningful clarity: a funded transition programme at Port Talbot, a strengthened trade protection architecture, a maturing electricity price support framework and a stated aspiration to return domestic production to 40–50% of UK demand.
For Scunthorpe, it provides almost none of these things. British Steel's Scunthorpe facility – the UK's last integrated steelmaking operation, operator of the country's only remaining blast furnaces and the sole domestic supplier of rail to Network Rail – is described in the strategy in terms of emergency intervention rather than strategic transformation. Parliament was recalled in April 2025 to pass the Steel Industry (Special Measures) Act. Significant government loans have been provided to keep the blast furnaces running. The government states it continues to work with British Steel's owners to find a "pragmatic, realistic solution." No transition pathway is defined, no timeline is set and no fiscal endpoint is stated.
An earlier analysis at SteelOnTheNet, published in July 2025, proposed green steel rerolling as the rational long-term configuration for the site. The proposal was to import billet from DRI producers and process it through Scunthorpe's existing rolling mills – eliminating raw material dependency and capital intensity while preserving rolling capability and customer relationships. That analysis remains sound in its essentials. What has changed since July 2025 is the electricity cost landscape: the British Industry Supercharger and the announced BICS scheme have materially improved the economics of electrified production at Scunthorpe, opening up a wider range of viable configurations than existed nine months ago. This article examines what that changed landscape means for the options available – and why the strategic decision that needs to be taken has still not been made.
The 2,700 direct employees at Scunthorpe, and the many thousands more in the regional supply chain, deserve better than the management of successive crises. A defined transition pathway – with proper worker support and community investment – is not a threat to employment at Scunthorpe. It is the only credible route to protecting it.
What the UK Steel Strategy Does – and Does Not – Say About Scunthorpe
The strategy's treatment of Scunthorpe is notable for what it omits as much as what it includes. The production asset table lists Scunthorpe's configuration simply as "2.5 Mt Blast Furnace" with no transition technology noted. Port Talbot, by contrast, is listed as "Transitioning to 3.2 Mt EAF." The strategy describes British Steel as the UK's only rail producer, supplying 80% of Network Rail's requirements, and its only heavy sections producer. These facts are presented as arguments for continued support rather than as inputs to a transition analysis.
The strategy notes that the government's intervention was necessary to prevent premature closure of the blast furnaces. This framing deserves scrutiny. A blast furnace losing approximately £700,000 per day, with no funded capital project to replace it and no private sector partner committed to co-investment, is not on a path to long-term viability. The government's emergency intervention in April 2025 prevented immediate closure – but intervention without a defined transition plan simply defers the question rather than resolves it. Without that plan, there is a real risk that change eventually arrives without the worker transition support, retraining funding and community investment that an orderly process would provide – and that Scunthorpe's workforce has every right to expect.
There is no discussion of rerolling as an option, no analysis of an EAF transition at Scunthorpe and no framework for evaluating competing configurations. The commitment to finding a "pragmatic, realistic solution" with British Steel's owners is unaccompanied by any definition of what a solution would look like, what timeline it would operate on or what conditions would be attached to continuing government financial support in the interim.
The wider analysis at SteelOnTheNet on zombie mills and state aid is directly applicable here – and the pattern is documented in the European Steel State Aid Database, which covers three decades of government intervention. The pattern is precise: a facility loses money, a government provides support framed as temporary, the facility survives another cycle and the process repeats. Each intervention is described as emergency management rather than strategic choice. Decades of European steel history demonstrate that this pattern does not resolve itself without a deliberate decision to define an endpoint. The UK Steel Strategy, for all its genuine strengths, does not yet set out that framework for Scunthorpe – a gap this analysis suggests warrants early attention.
The Changed Electricity Landscape
Before assessing the options available to Scunthorpe, it is worth noting that the policy landscape has shifted materially since the original rerolling analysis was published in July 2025 – in ways that affect the commercial viability of all three electrified configurations considered below.
The UK's electricity subsidy architecture has developed substantially since July 2025. The British Industry Supercharger launched in April 2024 but was not fully operational until April 2025 with its Network Charging Compensation (NCC) element. The 90% NCC level took effect in April 2026. BICS was announced as part of the Modern Industrial Strategy in June 2025 and is planned for 2027, though eligibility criteria remain unconfirmed at the time of writing.
This architecture does not help blast furnace operations at Scunthorpe in any meaningful way. The energy intensity factor for integrated steelmaking is 0.178 MWh per tonne of crude steel, compared to 0.435 for EAF – figures cited in the strategy's own Annex B, sourced from SteelOnTheNet Cost Models. The electricity saving from the Supercharger at blast furnace intensity is roughly £7–9 per tonne of crude steel – a marginal improvement against daily losses driven by coal, ore and capital costs that the electricity schemes cannot touch.
What the changed architecture does affect is the economic viability of electrified production at the site – whether rerolling or EAF. Post-Supercharger at 90% NCC, eligible producers face approximately £86 per MWh. Once BICS is operational from 2027, qualifying manufacturers would face approximately £46–51 per MWh – broadly comparable to Germany and better than France on the strategy's own modelling. For the first time, a Scunthorpe EAF or rerolling operation can be evaluated on commercial rather than purely political grounds.
Three Configurations | An Updated Assessment
Three configurations now merit serious evaluation for Scunthorpe's future. They are not mutually exclusive in the long term, but they have different risk profiles, different capital requirements and different implications for employment and supply security in the near term.
Option A: Rerolling as the Near-Term Bridge
The rerolling configuration preserves the rolling mills, the metallurgical expertise and the customer relationships – including the Network Rail rail supply relationship – that are the foundation of employment at Scunthorpe. By importing green steel billet from H₂-DRI producers rather than producing primary iron on site, it eliminates the blast furnace operations that are structurally unviable, whilst keeping the processing and rolling operations – producing long steel products including rail, sections and merchant bar – that can support sustainable long-term employment. It provides immediate decarbonisation without the execution risk of a large capital project on an uncertain financing basis.
The electricity subsidy developments since July 2025 make rerolling modestly more attractive than before, since rerolling operations are electricity-intensive and post-Supercharger support reduces cost per tonne of processed steel meaningfully. Near-term billet and HBI supply is available from natural gas-based DRI producers in the Middle East, with whom European steelmakers already have well-established trading relationships. Emerging green steel billet supply from Scandinavian hydrogen-based producers is expected to reach commercial volumes by the mid-2020s, offering a genuinely low-carbon green steel supply option as Scunthorpe's transition matures. In the near term, imported billet provides a financially viable bridge that eliminates the coal and ore dependency driving current losses. The strategy's own acknowledgement that near-term primary iron needs can be met through imports of DRI products validates this supply logic, applying to Port Talbot the same reasoning that applies here.
Option B: Full EAF Transition
A full EAF transition at Scunthorpe is significantly more viable in the April 2026 electricity environment than it was at the time of the original analysis. However, three specific challenges apply that do not affect Port Talbot equally.
The first is capital and ownership. The strategy estimates EAF transition at Scunthorpe would require approximately £1.25bn – a capital commitment whose underlying cost structure can be explored in the EAF Cost Model, and whose scale is set in context by the steel industry capital investment database. The Port Talbot transition has a defined private sector partner – Tata Steel – with a balance sheet and strategic commitment to the site. British Steel's ownership position is fundamentally different: its owner Jingye has not to date committed to large-scale capital investment at the site, and no committed private sector partner for a Scunthorpe EAF has come forward. The ownership question is inseparable from the investment question.
The second is product specification. Scunthorpe's primary distinctive product is rail – a demanding specification requiring very low residual element content. EAF-produced rail is technically feasible but requires either exceptionally clean scrap or DRI supplement to dilute residuals to acceptable levels. The strategy acknowledges that domestic demand for high-quality low-residual scrap could rise by seven to eight times as new EAFs come online, and that scrap quality infrastructure is not yet in place. A Scunthorpe EAF making rail would compete for the highest-quality scrap simultaneously with 7 Steel in Cardiff, Tata Steel at Port Talbot and Speciality Steel UK in Sheffield.
The third is market overlap. 7 Steel's Cardiff facility already operates a 1.2 million tonne EAF producing sections and long products. The differentiated product that justifies a Scunthorpe EAF specifically is rail. Network Rail currently procures around 200,000 tonnes of rail annually from Scunthorpe – insufficient alone to underwrite a £1.25bn EAF investment. A broader long products strategy including heavy sections, and government procurement commitments aligned accordingly, would be required to make the business case credible.
Option C: Phased Managed Transition
The most strategically coherent option is a phased managed transition that uses rerolling as a near-term bridge while creating the conditions for a longer-term EAF investment decision. The blast furnaces would be taken out of service on a defined timeline, and rerolling operations would commence using imported billet to maintain production and preserve customer relationships. In parallel, the government would invest in the scrap quality infrastructure and DRI supply logistics that a future Scunthorpe EAF would require. A decision on whether and when to proceed with an EAF would then be made on commercial grounds as those infrastructure conditions are met.
This approach requires the government to state explicitly that the blast furnaces will not continue indefinitely, set a defined timeline for their decommissioning and establish a transition fund for workers and communities – structured along the lines of the Port Talbot Transition Board – activated from a specific date rather than in response to a crisis. At Port Talbot, that board allocated £102m to worker support, retraining and community regeneration, and secured 5,000 long-term jobs through trade union involvement from the outset. Scunthorpe's workforce deserves the same structured approach. Port Talbot demonstrates what is possible when transition planning begins early, with trade union partnership and adequate resourcing. That model is available for Scunthorpe too – but it requires the planning to begin.
The German coal phase-out model, examined in the SteelOnTheNet analysis of overcapacity barriers, provides the broader structural template: sunset clauses, declining support levels over time, verified equipment decommissioning and comprehensive regional development investment. Its lesson is not that such transitions are easy – it is that they are manageable when properly resourced and defined from the outset, and unmanageable when deferred until crisis forces the issue.
The Employment Argument for Managed Transition
Continued blast furnace operation on the current basis is the employment risk, not the solution to it. A facility losing £700,000 per day, with no funded capital project, no committed private sector partner and no defined transition strategy, is not a stable employment platform. Without a managed transition plan, there is a real risk that change arrives under emergency conditions – with less funding available, less planning time and worse outcomes for workers than an orderly process would deliver.
Rerolling and phased transition preserve more jobs more durably than the status quo. Rerolling maintains the rolling mills, the metallurgical expertise and the customer relationships that employ people at Scunthorpe. It eliminates the blast furnace operations – which are the unviable part – while keeping the processing and rolling operations that can be commercially sustainable. A managed transition with a Port Talbot-style transition board, worker retraining fund and community investment programme protects far more workers than an unplanned crisis closure.
At Port Talbot, a structured transition secured 5,000 long-term jobs, allocated £102m to worker support and community regeneration, and involved trade unions as partners throughout the process. Scunthorpe's workers and communities deserve the same. The only way to achieve it is to begin planning now – not after the blast furnaces fail commercially.
The Missing Framework
The electricity subsidy developments since July 2025 change the option space for Scunthorpe. They do not, by themselves, resolve the fundamental question. The reason the question remains unresolved is not a lack of viable options – it is the absence of a decision framework for choosing between them.
What a transition framework for Scunthorpe would need to address is four things. First, a defined endpoint for blast furnace operations: a timeline from which transition planning, worker support and community investment can be organised. Second, conditions attached to continuing public financial support: milestones, decarbonisation commitments and sunset clauses that make loans time-limited rather than open-ended. Third, a procurement commitment that anchors the commercial case for domestic rail and sections production – whether from rerolling or an eventual EAF. Fourth, an ownership resolution: whether Jingye remains as operator, whether a new private sector partner is sought or whether a form of government stewardship continues – and if so on what terms – is inseparable from any investment decision.
Without these four elements, the analysis presented in this article remains theoretical. Rerolling is the most commercially viable near-term option. An EAF transition is more viable than it was, and merits serious commercial evaluation. A phased managed transition combining both is the most strategically coherent path. None of these outcomes will materialise through market forces alone or through continued emergency intervention. They require a transition framework – and developing one, in partnership with workers, communities, trade unions and Parliament, is the most constructive next step the strategy could take.
Conclusion
The UK Steel Strategy is right that Scunthorpe matters to national supply security. It is right that the rail supply relationship with Network Rail has genuine strategic significance. It is right that the communities of North Lincolnshire deserve a long-term plan rather than the management of successive crises. On these points the strategy and this analysis agree entirely.
Where they diverge is on what a long-term plan means in practice. The strategy's implicit answer is continued support for the existing configuration while a solution is sought. This analysis's answer – updated for a materially changed electricity cost environment – is that the viable long-term configurations for Scunthorpe all involve moving away from blast furnace primary steelmaking. The choice between rerolling, EAF transition and a phased combination of both should be made on commercial and strategic grounds. That means a defined timeline, appropriate conditionality on public support and proper transition investment for workers and communities.
The electricity subsidy architecture introduced since July 2025 has materially improved the commercial viability of all three electrified options – that is a genuine and significant change. It does not, however, substitute for a transition framework that sets out a pathway for the site. The constructive next step is to move from emergency management to strategic planning – and to do so in partnership with workers, communities, trade unions and Parliament.
SteelOnTheNet
25 March 2026
Sources and Notes:
1 Department for Business and Trade (2026). The UK Steel Strategy, CP1532. London: HMSO, March 2026. The strategy sets out the government's vision for the steel sector, investment commitments, trade measures, and decarbonisation framework. Data on domestic supply share, site-level production capacities, and electricity price modelling are derived from the strategy and its annexes. Available at: www.gov.uk/official-documents.
2 Kotas, A.M. (2025). 'British Steel Scunthorpe: Strategic Turnaround from Integrated Steelmaking to Green Steel Rerolling.' SteelOnTheNet, 2 July 2025. DOI: 10.5281/zenodo.18927401. The paper proposed green steel rerolling as the rational long-term configuration for Scunthorpe and assessed the case for blast furnace reinvestment as commercially unviable. The electricity cost data in that paper reflected pre-Supercharger or early-stage Supercharger conditions; the structural arguments regarding blast furnace economics are unaffected by subsequent policy developments.
3 Department for Business and Trade and Department for Energy Security and Net Zero (2025). Energy Intensive Industries: Consultation on the Proposed Uplift to the Network Charging Compensation Scheme. London: HMSO, October 2025. Confirms the increase in network charge compensation from 60% to 90% for eligible energy-intensive industries and provides the electricity price modelling used in Annex B of the UK Steel Strategy. Energy intensity factors of 0.435 MWh/t for EAF and 0.178 MWh/t for integrated blast furnace production are sourced from SteelOnTheNet Cost Models and cited in the strategy's Annex B methodology.
4 OECD (2025). OECD Steel Outlook 2025. Paris: OECD Publishing. Projects global steel excess capacity reaching 721 million tonnes by 2027 and analyses the structural drivers of persistent overcapacity including state subsidy and the dual barrier structure of entry and exit costs in the industry.
Editorial note: The UK Steel Strategy devotes three sentences to Speciality Steel UK, whose Stocksbridge and Rotherham sites contain some of the most genuinely strategic steel assets in the country. There is no assessment of strategic capability, no framework for the ongoing sales process and no lessons drawn from the ownership failure that preceded it. This series will return to that question in a forthcoming article.
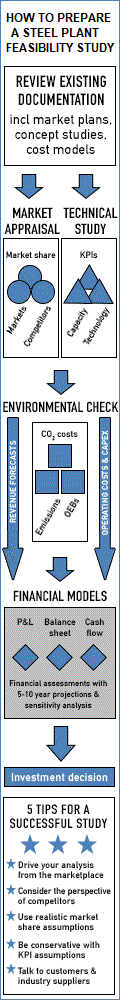
Facing this on a live project? Our Feasibility Study Service → Discuss a Project →
How to Cite This Article
Kotas, A.M. (2026) 'Scunthorpe Unresolved: What the UK Steel Strategy Leaves Unsaid', SteelOnTheNet. Available at: https://doi.org/10.5281/zenodo.19223974 (Accessed: 27 October 2026).
Author credentials:  ORCID iD