Executive Summary
Every government that owns a loss-making steel company faces the same question. Should it restructure the business first and then sell it? Or should it sell first and let the new owner do the hard work? The answer has shaped steel privatisations from Britain in the 1980s to Central Europe, Ukraine and Kazakhstan.
The question is far from closed. Pakistan, India and Italy all have large steel assets in some form of sale process today. Meanwhile several plants privatised decades ago have come back to the state. British Steel's Scunthorpe business, privatised in 1988, returned to public ownership in July 20261. Kazakhstan took back its largest steelworks in 20232. Serbia bought back Smederevo for one dollar in 20123.
This article argues three things. First, restructuring is not one task but three: restructuring assets, people and organisational structure. Second, each sequence carries hidden costs. Restructuring first takes time and effort, and may push the company in a direction that buyers do not want. Selling first passes the problem to someone else, but at a lower price and with weaker control over the outcome. Third, the choice is often driven by outside forces: election timetables and the steel price cycle can matter as much as business logic.
The practical answer is usually neither pure route. Governments should do the no-regret work before a sale, especially separating non-core activities and fixing governance. They should leave investment and product strategy to the buyer. Either way, a sale does not end the state's exposure, as the plants now back in state hands show.
Is the Age of Steel Privatisation Over?
The first great wave is largely finished. It began with British Steel in 1988, moved through Latin America, and peaked in Central and Eastern Europe in the decade before EU accession in 2004. A former World Bank official has traced the rise and later decline of privatisation within the Bank's own lending, with activity concentrated between 1990 and 20054.
Yet steel privatisation has not stopped. It has changed shape in two ways.
The Unfinished Cases
Some large state assets were never sold, or were offered repeatedly without success. Pakistan Steel Mills is the clearest example. A 2006 sale was struck down by the Supreme Court, and the plant has been closed since 2015. In 2015 the Cabinet Committee on Privatisation decided to offer it to the Sindh provincial government5.
In India, Rashtriya Ispat Nigam Limited (RINL) at Visakhapatnam is moving towards a piecemeal route, transferring individual units rather than selling the whole plant6. In Italy, the special commissioners for the former Ilva have run a tender for its assets, with decarbonisation among the criteria. Of 10 bids received in September 2025, only two covered the whole business7.
The Round Trips
Other plants have made a full circle from state to private and back again. British Steel was privatised in 1988 and later became part of Corus and then Tata Steel. Its Scunthorpe long products business, renamed British Steel in 2016, was nationalised in July 2026 after the government failed to find a buyer1. ArcelorMittal Temirtau, privatised in 1995, was sold back to a Kazakh state investment fund in December 2023 for US$286m, then renamed Qarmet2. The former Ilva, privatised in 1995, has been run by state-appointed commissioners since February 20247.
These round trips do not share a single cause. Smederevo, discussed below, fits the sequencing story most closely: a distressed plant was sold with its basic problems unresolved. British Steel shows the opposite case. It was thoroughly restructured before sale, yet part of it came back nearly four decades and several owners later. Temirtau returned after a fatal mine disaster in October 2023 and long disputes over safety and investment2.
The common lesson is wider than sequencing. A sale does not end the state's exposure. Sequencing matters, but so do the quality of the owner, the strength of its commitments and the point in the steel cycle. Together they decide whether a sale sticks.
When a Business Cannot Be Sold as It Stands
Before choosing a sequence, governments must face a harder question. Is the business saleable at all in its current form? Some are not.
A typical unsaleable steel company shares several features. It makes losses year after year. Its output is concentrated in low-value products, such as billets, wire rod or reinforcing bar, sold into crowded markets. Its costs are high, often because of old process routes, poor yields and heavy energy use. It also carries surplus staff, social obligations and unpaid debts.
No credible strategic investor will buy such a business as a going concern. The only bidders are likely to be asset strippers, or speculators hoping for state support later. Neither outcome serves the state or the workforce.
For these companies, the sequencing question largely answers itself. They are ripe for restructuring, and at least some of it must come first. The aim is not perfection. It is to create a core business that a serious buyer can value, finance and run.
What Restructuring Actually Involves
Debates about sequencing often treat "restructuring" as a single, vague task. In practice it has three separate dimensions. Each has its own timescale, cost and political sensitivity.
1. Restructuring Assets
Asset restructuring decides which plants, lines and facilities have a future. It often means closing a blast furnace, a rolling line or an entire site. The most common reason is simple: capacity is too large for the local market, a problem that is often harder to exit than to create.
When a plant is sized for a planned economy or a bygone boom, it cannot sell its full output nearby. Surplus tonnes must travel further to find buyers, and freight costs eat into margins. At the same time, a large plant may have outgrown its local raw material base. Iron ore, coal and scrap must then come from further afield. The plant ends up paying freight twice, inbound and outbound. A smaller, well-located operation can often earn more than a large one that serves distant markets at thin margins.
Closure decisions are the hardest of all. They are visible, permanent and local. A closed blast furnace rarely restarts. That is why asset decisions are often delayed, and why they sit at the centre of the sequencing debate.
2. Restructuring People
People restructuring covers how many employees the core business needs, and what happens to the rest. It has several parts.
Spinning off non-core businesses. Many state steel companies grew far beyond steelmaking. The Soviet-era metallurgical kombinats of the 1990s were extreme examples. A single plant in the CIS might own a cement works, hospitals, housing, kindergartens, canteens, farms and sometimes an airfield. These so-called social assets often employed thousands of people.
Few strategic investors want this baggage. They want to buy a steel business, not a town. Separating non-core activities therefore does two jobs. It reduces the headcount of the core business, and it makes that business more attractive to buyers.
Supporting spun-off businesses. A spun-off maintenance, transport or catering unit rarely survives if simply cut loose. Successful programmes have created business incubators for these new firms. The incubator offers shared central services, such as accounting, payroll, personnel management and IT. The parent steel company often gives the new firms transitional supply contracts, tapering over two or three years. This gives them time to find other customers.
Management buyouts. Some non-core units, and occasionally smaller business units, can be sold to their own managers through a management buyout (MBO). Typical candidates include maintenance workshops, transport fleets, refractory services, engineering shops and small downstream processing lines. Managers already know the customers, the staff and the equipment. An MBO keeps local jobs and avoids a long sale process.
There is a caveat, however. World Bank research found that insider buyouts generally restructured less vigorously than sales to strategic investors8. MBOs therefore suit service and support units. They are rarely the right route for core steelmaking.
Removing management layers. State enterprises tend to build deep hierarchies. Decisions pass through many levels, and accountability blurs. Removing layers shortens decision chains and cuts overhead costs. The bigger prize, though, is often fixed costs rather than headcount.
Multiskilling. Traditional demarcation between trades means several workers attend to tasks that one trained person could handle. Multiskilling lets operators carry out routine maintenance and lets crews cover more equipment. It raises productivity without closing capacity, and is a staple of profit improvement programmes.
Employee concerns. This period is deeply unsettling for the workforce. Employees worry about job security, pensions and severance terms. In kombinat towns, housing, healthcare and schooling may all be tied to the plant. Staff transferred to spun-off firms fear losing their terms and conditions.
Rumours about possible buyers spread quickly. The best-qualified people often leave first, because they find other work most easily. Clear and early communication, agreed social packages and union involvement all reduce this risk. Poland's main steel privatisation could only be completed once the buyer had agreed a social package with 12 trade unions covering some 16,000 staff9.
3. Restructuring the Organisation
The third dimension is the organisational structure itself. A state steel company is often organised around production targets rather than profit. Restructuring may involve creating profit centres, separating sales from production and building cost accounting that shows which products make money.
It also involves stronger controls. A common step is to create an internal audit department reporting directly to the chief executive, and ideally to a board audit committee. This gives the chief executive an independent view of how money is actually spent. It also signals to potential investors that the business can be governed to commercial standards. Unlike asset closures, these changes are relatively cheap and rarely controversial. They are also among the changes buyers value most.
The Case for Restructuring First
The argument for restructuring before sale is straightforward. A cleaner, smaller, profitable business attracts more bidders and a higher price. The state also keeps control of the most sensitive social decisions.
British Steel: The Classic Model
British Steel is the textbook case. Under Ian MacGregor, appointed chairman in 1980, the corporation closed capacity on a large scale. His December 1980 plan alone aimed to cut a further 20,000 jobs and reduce steelmaking capacity to 14.4 million tonnes10.
The workforce, about 268,500 at nationalisation in 1967, fell to about 53,000 by the time of the 1988 sale. By then the company had moved from heavy losses to healthy profits10. The state had absorbed the closures, the strikes and the redundancy costs. Investors bought a functioning business.
Poland: Consolidate, Then Sell
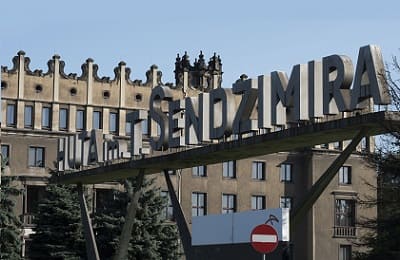
Poland followed a similar logic on a different timetable. Four major steelworks, including Huta Katowice and the Sendzimir works in Kraków, were merged into a single holding company, Polskie Huty Stali (PHS), in 2003. The government then sold about 70% to LNM Holdings, with a commitment to invest US$607m by 200911. Restructuring aid under the EU accession arrangements was tied to capacity reductions, giving the process a clear framework12.
Benefits of Restructuring First
- Higher sale price. Buyers pay more for a business with predictable costs and fewer liabilities.
- A wider field of bidders. More investors can assess and finance a clean business.
- State control of social terms. The government decides the pace of job cuts, rather than leaving it to a new owner.
- Fewer surprises after sale. Problems found before the sale can be fixed or priced in.
The Case for Privatising First
The opposite approach is to sell quickly and leave the problem to somebody else. This has real attractions for governments short of time, money or management capacity.
A World Bank study of Central and Eastern Europe found that privatisation itself was the single most important driver of enterprise restructuring. It also found that sale to a strategic investor generally produced stronger results than insider buyouts8. A later review noted that earlier efforts to reform state enterprises without changing ownership delivered modest results that were generally not sustained4. Wider academic surveys broadly confirm that privatised firms tend to become more efficient and more profitable13.
The logic is clear. A private owner has stronger incentives and better access to capital. A global steel group also has its own operating model, which it can apply quickly. Mittal's acquisitions across Central and Eastern Europe in the early 2000s largely followed this pattern. The group bought businesses that still needed heavy restructuring, then carried it out with its own methods.
Benefits of Privatising First
- Speed. The state stops funding losses sooner.
- Expertise. The buyer brings management skills the state may lack.
- Strategic fit. The buyer shapes the business to suit its own group strategy.
- Political distance. Unpopular decisions are taken by the new owner, not by ministers.
Politics: The Real Decider
In theory, sequencing should follow a careful assessment of the business. In practice, the choice is often largely political. The most important variable is frequently the election timetable.
Restructuring first front-loads the pain. Closures and redundancies happen on the government's watch, while the reward of a successful sale may fall to its successor. A government early in its term may accept that trade. A government near an election usually will not. It prefers either to delay everything or to sell quickly and announce a deal.
The record shows this pattern clearly:
- Britain. British Steel was sold in December 1988, comfortably after the 1987 general election. The painful restructuring had been done early, largely in the government's first term.
- Ukraine. Kryvorizhstal was sold in 2004 for US$800m to a group linked to the outgoing president. The incoming government annulled the sale. A televised re-auction in 2005 raised US$4.8bn11. Holding a transparent re-auction had been a campaign promise.
- Serbia. The HBIS agreement for Smederevo was signed live on state television, just days before an early general election3.
- Pakistan. Repeated changes of government and court rulings have kept Pakistan Steel Mills in limbo for two decades5.
Only the British case shows the electoral calendar shaping the choice between restructuring and selling. The others show it shaping when a sale happens and how clean it is. Both push the condition of the business down the list.
None of this makes political timing wrong in itself. Privatisation needs political consent to last, and a sale that lacks it may be reversed. The danger arises when the electoral calendar, rather than the condition of the business, decides the sequence.
Timing the Steel Cycle
The second outside force is the steel price cycle. Steel is a highly cyclical industry, and prices and margins can swing sharply within two or three years. Where the business sits in the cycle can tilt the decision either way.
When Prices Are Falling
In a downturn, losses at a state-owned producer mount quickly. Each month of delay costs the treasury more, which creates strong pressure to sell fast. Yet buyers are scarce and cautious in a falling market, and they bid low. A sale in a downturn therefore tends to bring a poor price and few serious bidders.
A downturn does have one advantage. The case for change is plain to everyone. Closures and job cuts are easier to justify when losses are visible. British Steel's deep restructuring in the early 1980s began in exactly such a crisis10.
When Prices Are Rising
In an upturn, the picture reverses. Losses shrink or turn into profits, and buyers compete for assets. The sale of PHS was completed in March 2004, at the start of a strong steel boom. The business made a record net profit of PLN1.7bn that year14. Kryvorizhstal's 2005 re-auction, at US$4.8bn, also came near a cyclical high11.
Rising prices carry their own trap, though. Better results can hide structural problems, and governments may lose the urgency to restructure at all. The weaknesses return when the cycle turns, often under a new private owner less willing to absorb them.
Buyers Read the Cycle Too
Smederevo shows both sides. U.S. Steel left in 2012 as markets weakened. HBIS bought the plant in 2016, believing the market would bottom out that year and then recover. Within six months the plant was back in profit15. The same asset looked worthless to one owner and attractive to another, largely because of timing.
The practical lesson is a simple rule of thumb. Where possible, restructure in the downturn, when the case for change is clearest. Sell into the upturn, when buyers pay most. This does not mean fitting a 5- to 10-year programme into one downturn. It means using the downturn for the no-regret steps set out below, which are far quicker than closures.
Few governments can time the cycle precisely. Even so, ignoring it can cost far more than any detail of the sale process.
A Practical Middle Way: Sequencing in Layers
Three decades of experience point to a more useful question. Not "restructure or sell first?" but "which parts of restructuring should come first?" The three dimensions above give a natural order.
Do Before the Sale: The No-Regret Steps
Some steps raise the value of the business for almost any buyer. They are also within the state's power to complete in a reasonable time.
- Separate non-core activities. Hospitals, housing, cement works, farms and canteens should be transferred to municipalities, sold to their managers, or set up as independent businesses. Incubator support helps them survive.
- Fix governance and controls. Create proper management accounts, an internal audit function reporting to the chief executive, and clear lines of responsibility.
- Remove obvious overhead. Cut surplus management layers and duplicated support functions.
- Clean up the balance sheet. Settle or ring-fence historic debts, tax arrears and legacy environmental liabilities so that buyers can price the business.
- Agree the social framework. Settle severance terms and pension arrangements in advance, with union involvement.
Leave to the Buyer: The Strategic Choices
Other decisions depend on the buyer's own strategy. The state should normally avoid locking them in.
- Major capital investment. New mills, product ranges and technology routes, including the route to low-carbon steelmaking.
- Market positioning. Which customers and regions to serve.
- Fine-tuning capacity. Beyond clear-cut closures of plant that has no future under any owner.
The Grey Zone: Asset Closures
Plant and line closures sit between the two. Where capacity is plainly too large for the market and the logistics do not work, early closure removes uncertainty and widens the field of bidders. Where the economics depend on a buyer's group network, closure decisions are better left to the buyer, backed by clear and enforceable commitments.
| Dimension | Before Sale | After Sale |
|---|---|---|
| Assets | Close plant with no future under any owner | Capital investment, technology route, product mix |
| People | Spin off non-core units, including through MBOs; agree social package; remove surplus layers | Multiskilling, productivity programmes, further fine-tuning |
| Organisation | Management accounts, internal audit, clear accountability | Integration into the buyer's group structure |
Source: SteelOnTheNet analysis. Data as of November 2026.
Lessons for Today's Cases
The live cases illustrate the same choices. Pakistan Steel Mills has been closed for years. Any buyer will now inherit a plant that needs rebuilding, not just restructuring. India's piecemeal approach at Visakhapatnam effectively restructures by sale, unit by unit. That may be workable, but it risks leaving the state holding the weakest parts.
The former Ilva tender attaches decarbonisation commitments to the sale. That approach depends heavily on whether such commitments can be enforced. It also tests the rule set out above. Technology choice is normally best left to the buyer, but decarbonisation is now a public goal as well as a business decision.
Britain now faces the question afresh. British Steel is back in public hands, at a reported cost of over £1m a day1. At some point the government will need to decide whether to restructure the business itself, or to find a partner to do so.
Conclusion: Sequence the Work, Not Just the Sale
Restructuring first and privatising first are not really rival philosophies. Each is a bet about who is best placed to do which part of the work. The state is usually best placed to separate social assets, settle legacy liabilities and set the social terms. Buyers are usually best placed to decide on investment, technology and markets. Asset closures fall between the two.
The worst outcomes come from blurring this division. A state that invests heavily before a sale risks spending money that no buyer will repay. A state that sells without fixing the basics risks seeing the asset return, as Smederevo did. Where the electoral calendar or the steel cycle sets the pace, the condition of the business often comes last.
Governments planning a steel sale today should start by asking a narrower question: which tasks must the state do before a buyer will commit? Do those tasks well and quickly, ideally while prices are low. Leave the strategic choices to the owner who will live with them.
Britain is now the test case. It owns a single blast furnace site that needs a new technology route, heavy investment and, in time, a partner.
The logic of this article points one way. Do the no-regret work now: governance, legacy liabilities and the social framework. Then let a partner shape the technology route it will have to run. Choosing the route first and seeking a buyer second risks restructuring in a direction no buyer wants. That is how to make a privatisation stick, and how to avoid the next round trip.
SteelOnTheNet
5 November 2026
Facing this on a live project? Our Restructuring Service → Discuss a Project →
How to Cite This Article
Kotas, A.M. (2026) 'Restructure First, Sell Second? Thirty Years of Steel Privatisation Sequencing', SteelOnTheNet. Available at: https://www.steelonthenet.com/insights/steel-privatisation-restructuring.html (Accessed: 5 November 2026).
Author credentials:  ORCID iD